When Everyone Else Seems Rich: Social Comparison and Financial Pressure
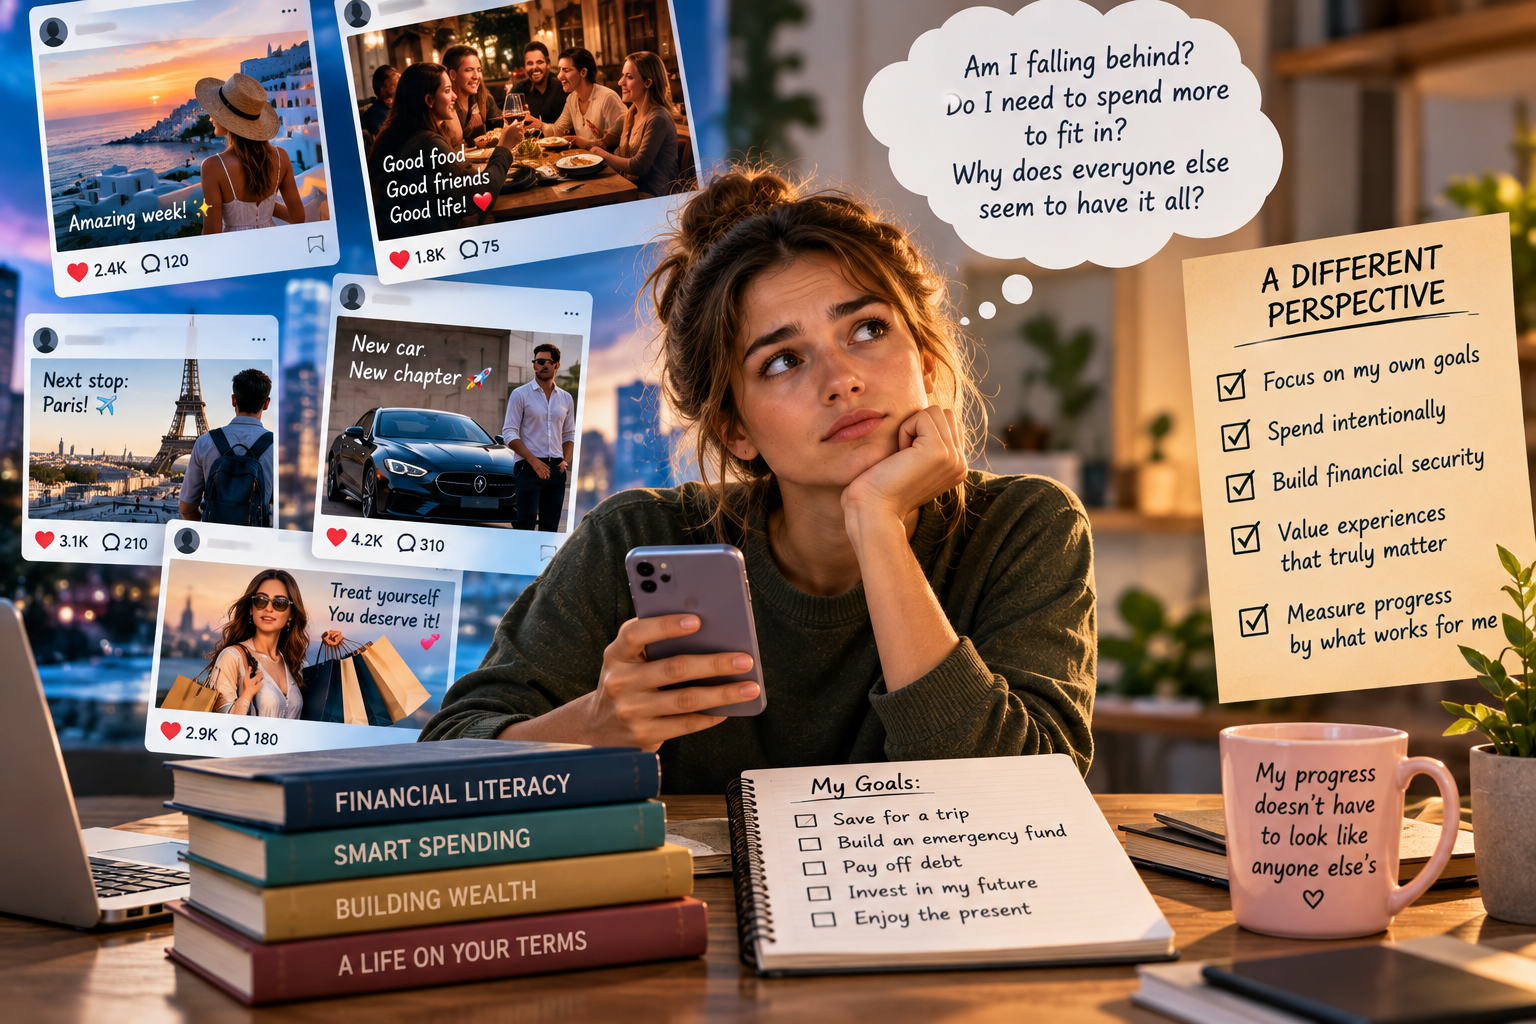
Scrolling through social media can sometimes leave us with a strange impression: everyone else seems to be doing better financially. Friends are travelling abroad, colleagues are buying new cars, influencers are showing off expensive lifestyles, and people our age appear to be enjoying opportunities that still feel out of reach. Even when we know that social media does not tell the whole story, it can be difficult to avoid comparing our own lives with what we see on the screen.
This comparison can have a surprisingly strong influence on how we think about money. Financial decisions are rarely based on numbers alone. They are also shaped by our expectations, emotions and perceptions of what a successful life should look like. When the people around us appear wealthier, more successful or more financially secure, it can change how we evaluate our own circumstances—and what we feel we should be spending.
One of the main problems with social comparison is that it creates a distorted picture of reality. Social media usually presents carefully selected moments rather than a complete financial picture. We see the holiday, but not the credit card bill. We see the new car, but not the monthly repayments. We see the restaurant dinner, but not the compromises someone may be making elsewhere in their budget. Even when the things we see are genuine, we rarely know how they were financed or what they cost in the long term.
As a result, we end up comparing our everyday reality with someone else’s carefully selected highlights. This can create the impression that we are falling behind, even when our financial situation is perfectly reasonable for our circumstances.
For young adults, this pressure can be particularly difficult to navigate. Early adulthood is often a period of uncertainty, when people are beginning their careers, earning their first regular income and trying to establish their independence. Financial situations can differ enormously depending on family support, housing costs, employment opportunities and personal circumstances. Yet social expectations can make it seem as though everyone should be reaching the same milestones at roughly the same time.
When these expectations become internalised, spending can turn into a way of keeping up. Someone might choose a more expensive restaurant because their friends do, purchase clothes to fit in with a particular social group, or spend money on a holiday they cannot comfortably afford because they do not want to miss out. In other cases, people may feel pressure to own the latest phone, follow particular trends or maintain a lifestyle that does not reflect their actual financial priorities.
These decisions are not necessarily driven by carelessness. Often, they are connected to a basic human desire to belong. Spending money can become a way of participating in social life, expressing identity or avoiding the uncomfortable feeling of being left behind. The difficulty arises when the desire to meet external expectations begins to override personal financial goals.
The consequences are not always immediate. One expensive purchase may not create a serious problem, but repeated attempts to maintain a lifestyle beyond one’s means can gradually undermine financial stability. Savings are postponed, credit becomes more tempting, and future goals are sacrificed to support present consumption. What begins as an effort to feel included can eventually become a source of financial stress.
There is also a less obvious cost: the loss of confidence in our own decisions. When we constantly compare ourselves with others, we may start judging our financial progress according to standards that have little relevance to our personal circumstances. Saving money can feel unimpressive when others appear to be spending freely. Choosing an affordable holiday may feel disappointing when friends are visiting distant destinations. Building an emergency fund can seem less exciting than purchasing something visible and immediate.
Yet financial wellbeing is not a competition, and visible consumption is not a reliable measure of financial security. Someone who appears wealthy may have substantial savings, considerable debt or very little financial resilience. Without understanding their circumstances, it is impossible to know. More importantly, their financial choices may have little connection to what would be appropriate for us.
Developing a healthier relationship with money therefore requires a shift in perspective. Instead of asking whether we can afford to keep up with others, we can ask whether a particular expense supports our own priorities. Instead of measuring progress through possessions or experiences, we can consider whether we are becoming more financially secure, building useful skills, reducing unnecessary debt or moving towards goals that genuinely matter to us.
This does not mean avoiding social activities or refusing to spend money on enjoyable experiences. Financial literacy is not about eliminating pleasure from life. It is about making conscious decisions and recognising the difference between spending because we genuinely want something and spending because we feel that we are expected to want it.
A practical starting point is to identify the situations in which social pressure affects our spending. Do we tend to spend more when we are with particular friends? Do certain social media accounts make us dissatisfied with what we own? Have we ever bought something mainly because we did not want to feel different from others? These questions can help reveal patterns that might otherwise remain unnoticed.
The next step is to establish personal financial priorities. Having a clear reason to save, spend or avoid unnecessary debt makes it easier to evaluate external pressure. When we know what we are working towards, we are better equipped to recognise that someone else’s priorities do not have to become our own.
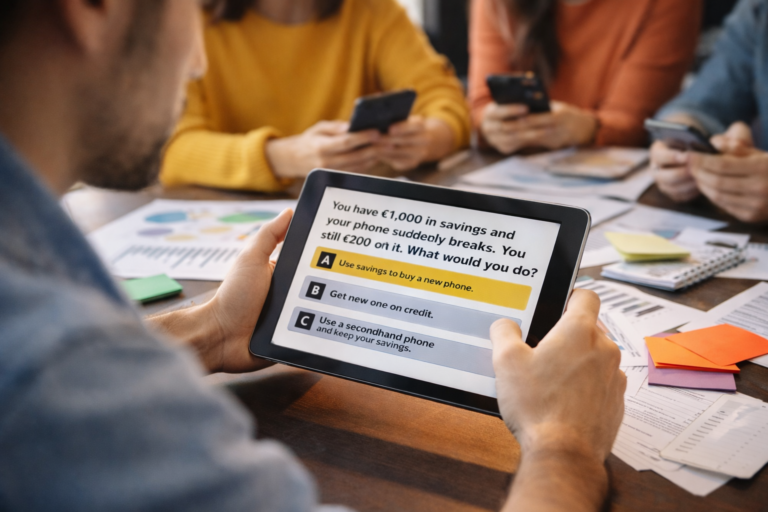
This behavioural perspective is closely connected to the FINMAN+ project. Through scenario-based learning, the project encourages learners to explore realistic financial situations, examine the influences behind their decisions and consider the consequences of different choices. Situations involving peer pressure, lifestyle expectations or the temptation to spend beyond one’s means can help participants understand how social influences affect financial behaviour and practise making decisions that reflect their own circumstances and goals.
Ultimately, financial independence involves more than earning enough money to cover our expenses. It also means developing the confidence to make choices that suit our lives, even when those choices differ from what others appear to be doing.
The next time it seems that everyone else is getting richer, buying more or living better, it may be worth remembering one simple thing: you are seeing their lifestyle, not their balance sheet.
Your financial progress does not need to look impressive to anyone else. It needs to work for you.