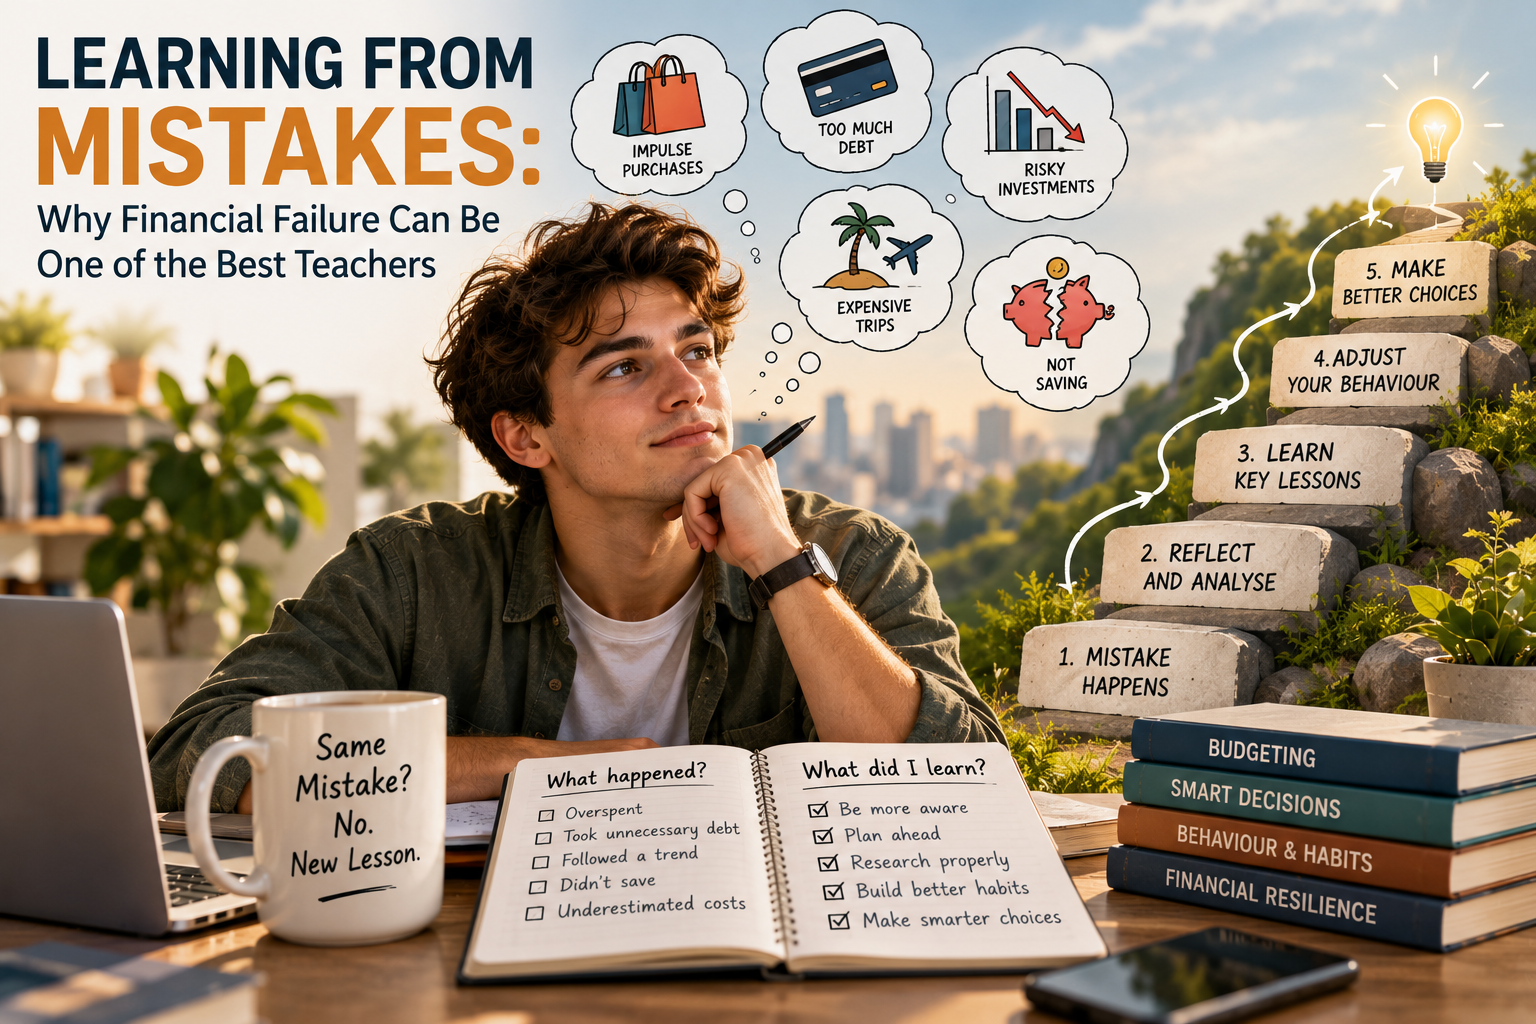
Learning from Mistakes: Why Financial Failure Can Be One of the Best Teachers
Financial education often presents money management as a series of rules: spend less than you earn, save regularly, avoid unnecessary debt, plan for the future. These principles are useful, but they can create an unrealistic impression that good financial decisions are simply a matter of knowing the rules and following them consistently.
Real life is considerably messier.
People overspend. They take on debt they later regret. They make purchases they cannot really afford, trust questionable financial offers, forget to save, or underestimate how quickly unexpected expenses can accumulate. For young adults in particular, some of these experiences may be unavoidable parts of learning how to manage money independently.
A financial mistake can certainly have negative consequences. But the mistake itself does not necessarily determine what happens next. What matters is whether the experience becomes something to hide and repeat, or something to understand and learn from.
This distinction is important because mistakes often provide something that theoretical knowledge cannot: feedback.
Imagine someone who repeatedly spends too much at the beginning of the month and then struggles towards the end. They may already know that they should budget more carefully. Simply telling them this again is unlikely to change much. But experiencing the consequences of that pattern may reveal something more useful: when and why the overspending happens, which purchases are difficult to control, and what kind of system could prevent the same situation from happening again.
The same principle applies to other financial decisions. A person who takes on an expensive loan may learn to look more carefully at the total cost of borrowing. Someone who repeatedly postpones saving may realise that waiting until the end of the month rarely leaves anything available to save. A person who follows an exciting investment trend without understanding the risks may discover the importance of researching an opportunity before committing money.
These experiences can be uncomfortable, but they can also make financial concepts much more tangible.
There is, however, an important difference between learning from a mistake and simply experiencing a negative outcome. A mistake becomes useful when it is followed by reflection. What happened? Why did I make that decision? What information did I overlook? Was the problem caused by a lack of knowledge, a habit, an emotional reaction, or pressure from other people? What could I do differently next time?
This process turns an isolated event into a learning experience.
It also challenges the idea that financial education should always provide learners with a single “correct” answer. Real financial decisions rarely happen in perfectly controlled circumstances. People have competing priorities, limited information, unexpected expenses and different personal circumstances. Learning how to recognise trade-offs and understand consequences can therefore be more valuable than simply memorising financial rules.
This is particularly relevant for young adults, who are often making important financial decisions for the first time. Their first salary, first rental contract, first loan, first significant purchase or first investment can all become learning experiences. Expecting perfect decisions from the beginning is unrealistic. What matters is developing the ability to assess decisions, recognise mistakes and adjust behaviour.
Financial resilience grows from this process. It does not mean avoiding every financial difficulty. Instead, it involves developing the knowledge and confidence to respond when something goes wrong.
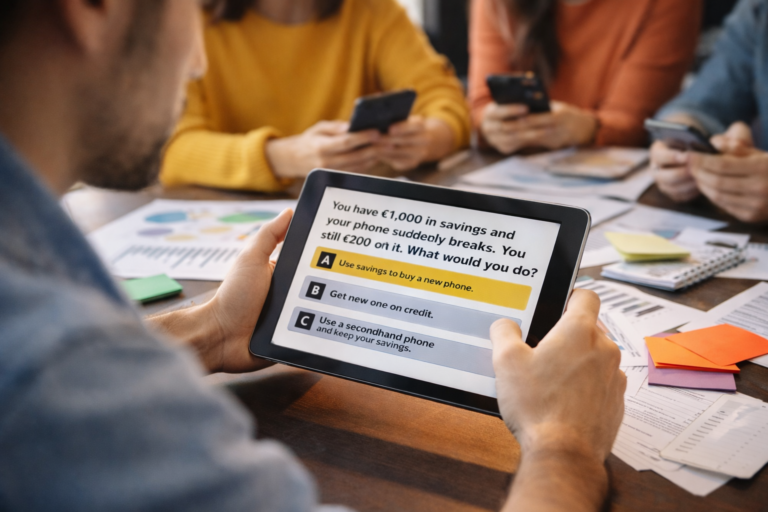
This is also where scenario-based learning can play an important role. Instead of waiting for learners to encounter every financial mistake in real life, educational scenarios can allow them to explore difficult situations in a safe environment. They can make a decision, see its potential consequences, reconsider their approach and discuss alternative choices without experiencing the actual financial cost.
Within the FINMAN+ project, this principle is particularly relevant. The project uses scenario-based learning to move financial education closer to the situations in which people actually make decisions. By allowing learners to engage with realistic financial challenges, reflect on their choices and consider different outcomes, the learning process becomes more experiential and connected to everyday life.
The objective is not to encourage people to make financial mistakes. It is to create an environment in which mistakes can become part of learning rather than sources of shame or avoidance.
After all, financial competence does not mean getting every decision right. It means becoming better at recognising risks, understanding consequences, adapting to changing circumstances and making more informed decisions the next time.
Sometimes the most valuable financial lesson is not the one we learn from a textbook.
It is the one we remember because we have experienced it ourselves.